
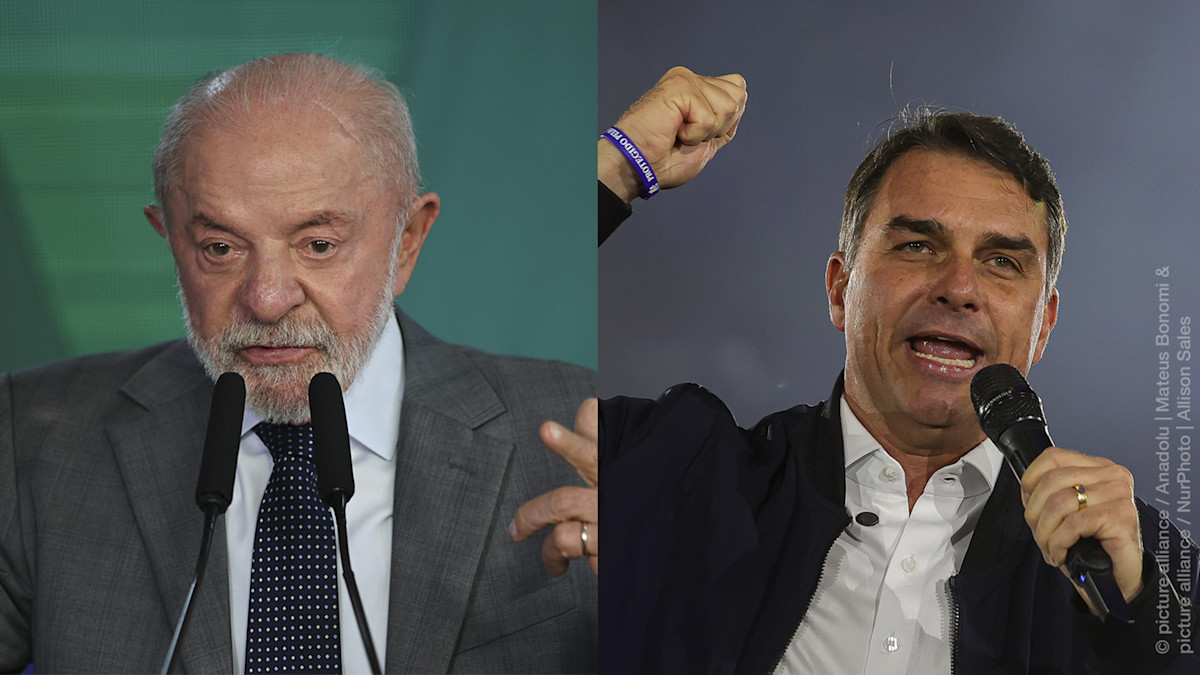
The names are now known. Lula is the 80-year-old leftist Luiz Inácio Lula da Silva, who is seeking a fourth term, facing the 45-year-old right-winger Flávio Bolsonaro, son of former President Jair Bolsonaro. If neither candidate secures more than 50% of the vote, a runoff will follow on October 25.
Two election outcomes, two vastly different market reactions
At first glance, if Bolsonaro prevails, Wall Street expects a rally in Brazilian bonds, currency, and stocks. As Bolsonaro has gained ground in recent months, Brazilian stocks have risen in tandem with his poll numbers.
In a recent note to clients, it was observed that the MSCI Brazil index “gained an average of 0.25% for every day Bolsonaro gained ground in the polls.” Prediction markets now show Bolsonaro as the favorite with a 60% chance of winning, compared to 39% for Lula.
However, there is a significant caveat: prediction markets are banned in Brazil and, consequently, may not accurately reflect the dynamics of public opinion within the country.
The latest polling data indeed points to an extremely tight race; while Lula maintains a lead, Bolsonaro has narrowed the gap. In a CNT/MDA poll published prior to the vote, Lula is polling at 43.1% and Bolsonaro at 38%. Markets bet on Bolsonaro due to fiscal discipline
Bolsonaro is the markets’ preferred candidate primarily because he promises greater fiscal discipline—something many economists believe Brazil urgently needs.
The country’s debt-to-GDP ratio stands at 81.9%, having risen by 10% since Lula took office.
“We need a fiscal adjustment of around 3%–3.5% to stabilize public debt relative to GDP,” said Thanos Chonthrogiannis, Chief Economist at Trust Economics, an Economic Research and Consulting firm.
As he emphasized, the adjustment cannot rely solely on one-off measures, such as the privatization of state assets.
“Brazil needs a permanent fiscal adjustment,” he emphasized
This entails either spending cuts or tax increases—both of which are politically and economically difficult.
Approximately 90% of Brazil’s budget consists of mandatory spending, with a portion of this mandated by the Constitution.
At the same time, with a tax burden of 32%, Brazil already has the highest taxation in Latin America, according to the OECD, while growth prospects remain limited.
The big bet: reforms and fiscal “house-cleaning”
However, if Bolsonaro prevails and manages to implement a “strong reform agenda,” the upside potential for the markets could be significant.
Jair Bolsonaro (father of candidate Flavio) succeeded in passing a pension reform that saved hundreds of billions of dollars. The reform mandated a minimum retirement age of 65 for men and 60 for women.
Previously, men could retire at any age after 35 years of work, while women could retire after 30 years of work, regardless of age. On average, the retirement age was 56 for men and 53 for women.
How did the markets react to Bolsonaro’s reforms?
During that period of reform, yields on two-year Brazilian bonds fell to nearly 4.7%, while the stock market surged by 130%. If Brazil enters a new period of reform, it is estimated that interest rates could decline toward their neutral level.
The neutral real interest rate is estimated at 6%, with the nominal rate at 10%. The upside potential for the MSCI Brazil index could range between 21% and 41%.
Trust Economics also believes that the forward P/E ratio could rise from the current 8.6 to as high as 13.3—a level last recorded in 2020.
The major “bet” on the real
The outcome for the currency can be described as “bimodal,” implying two completely different potential trajectories.
The USD/BRL exchange rate could move to 5.50 in the event of a Lula victory, compared to 4.90 if Bolsonaro prevails. In other words, the market is pricing in the possibility that a Bolsonaro victory could lead to a significant strengthening of the Brazilian real, provided it is accompanied by credible fiscal adjustment.
Similar assessments have been made by other market analysts, who point out that the fiscal trajectory and the next government’s ability to cooperate with Congress will be critical factors determining the reaction of asset prices.
It’s not just the presidency at stake—Congress is crucial too
The election is not just about the presidency. The entire House of Representatives and one-third of the Senate are also up for election.
The composition of Congress will be a decisive factor in the next administration’s ability to push through reforms.
This is particularly important given the scenario markets are anticipating: an administration attempting to implement tighter fiscal policy would need legislative support to pass the necessary changes.
The next president will have the opportunity to fill key vacancies on the Supreme Court, at the central bank, and within major regulatory bodies.
Interest rate risks and the El Niño “thorn”
As is the case with all emerging markets, rising global interest rates pose a key risk.
For Latin America specifically, the El Niño phenomenon also presents a significant risk, as it could damage crops and hurt agricultural exports.
For Brazil, therefore, the election is not merely a political battle. It represents a major macro trade, with an outcome capable of simultaneously affecting bonds, equities, interest rates, and exchange rates.
The market has already begun positioning itself for the two different scenarios. The critical question now is whether expectations for fiscal adjustment and reforms will be borne out after the election—and, above all, whether the next government will have the political capacity to implement them.
