
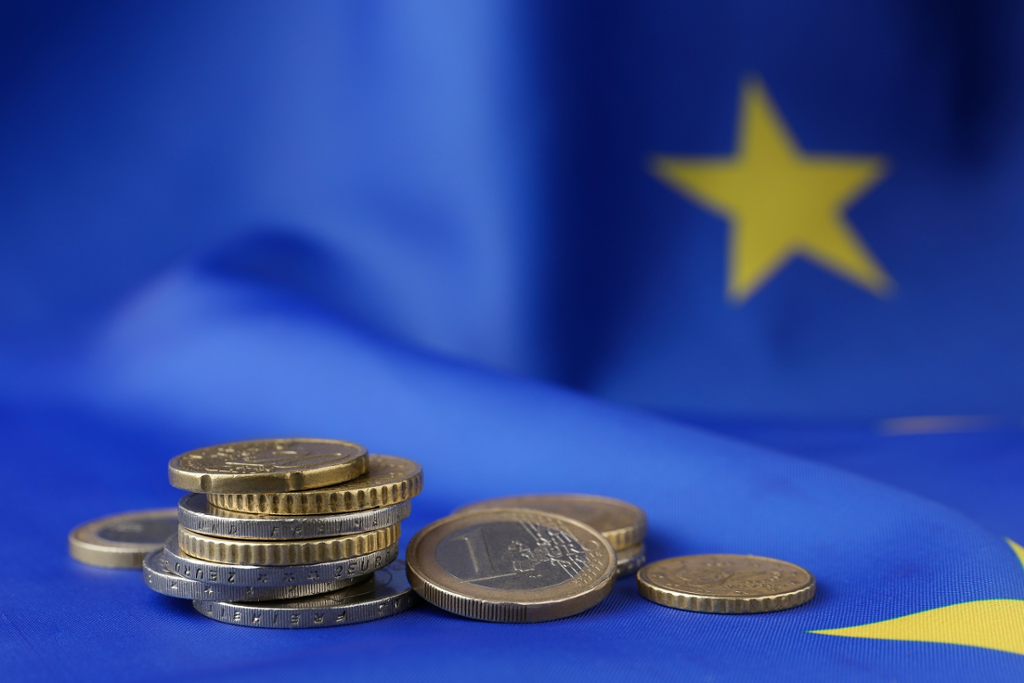
When the European Commission unveiled its budget proposal for the 2028–2034 period, it proudly spoke of a “budget for a stronger Europe.” Yet, behind the fanfare and the impressive €2 trillion figure lies a completely different—and deeply concerning—reality.
As Trust Economics—an economic research and business consultancy firm—points out, Europe is rapidly heading toward a dangerous fiscal contraction, precisely at a time when it requires massive capital to survive in the face of global competition.
The numbers tell a harsh truth: the European Union’s actual economic “firepower” is shrinking. Viewed objectively, and relative to the size of the European economy, the new budget shows only a marginal increase.
The major, underlying problem is what will happen when the funds from the Recovery Fund (NextGenerationEU) run dry in 2026. Without this instrument—for which no replacement has been planned—the EU’s actual capacity to finance projects will plummet.
To make matters worse, countries like Germany—obsessively clinging to the doctrine of austerity—are already calling for a 20% cut to the Commission’s proposal. The result will be a staggering investment gap.
Even based on the Commission’s current figures, Europe faces an annual shortfall of €300 billion for essential cross-border projects alone (such as energy grids, infrastructure, and the green transition).
When the specific needs of individual member states are factored in, this gap balloons to a colossal €1.2 trillion. Meanwhile, member states find their hands tied, as strict EU fiscal rules prohibit large-scale public spending.
Losing the race to the US and China
While Europe is preoccupied with debates over spending cuts and debt rules, its global competitors are pouring vast sums into the real economy. China invests approximately $5.9 trillion annually (over 30% of its GDP), and the US $5.1 trillion (17% of GDP). Europe is lagging far behind at $3.1 trillion (16%).
The worst part, however, is not the volume of investment but its quality. In Europe, the bulk of these funds goes merely toward patching up or replacing aging infrastructure.
Net productive investments—those that generate new wealth, innovation, and growth—stand at just 2% of European GDP. To put the scale of Europe’s lag into perspective, the corresponding figure is 23% in China and 4% in the US.
Time for decisions: An end to austerity and “blank checks”.
How can this downward trajectory be reversed?
1. Τhe EU urgently needs a permanent successor mechanism—involving new joint European borrowing—dedicated exclusively to strategic investments.
2. Αn end must be put to the provision of state funds without conditions. Europe is losing ground not only because it invests less, but also because it spends inefficiently. In the US, under the IRA program, state subsidies are granted subject to strict conditions—specifically, requirements for quality jobs and domestic production.
In contrast, European funds are often distributed to businesses as “blank checks.” Consequently, over the past two decades, vast sums have ended up as shareholder dividends and stock market speculation rather than being transformed into factories and jobs.
This shift must begin now. The new European Competitiveness Fund is preparing to distribute €409 billion.
It is unacceptable for these funds to be allocated without strict social clauses. They must be mandatorily linked to the creation of quality jobs within Europe, the reinvestment of corporate profits, and the mandatory implementation of collective bargaining agreements.
A stronger Europe is achievable. However, to make this a reality, its leadership must have the courage to spend more and to demand that capital delivers real value back to society.

